Use this pension drawdown calculator to see how long your pension pot could last if you take an income from it while it stays invested. Enter your pot, the income you want, expected growth and your other income, and it shows the age your money runs out and the tax on your withdrawals.
Your drawdown plan
- Tax-free cash
- –
- Money lasts until age
- –
- Tax on year 1 income
- –
- Year 1 income after tax
- –
| Income taken | Pot at end of year |
|---|
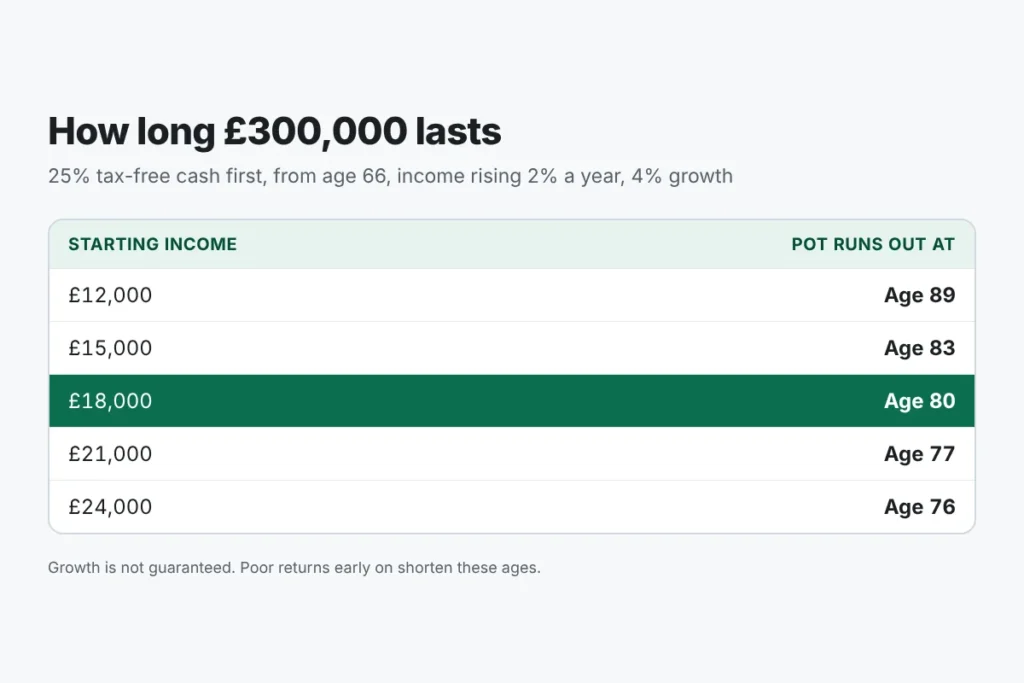
In the example, a £300,000 pot with £75,000 taken as tax-free cash, paying £18,000 a year rising by 2% and growing at 4% after charges, lasts until about age 80.
How to use the drawdown pension calculator
- Enter your pot and choose whether to take 25% tax-free cash at the start.
- Enter the yearly income you want to take before tax.
- Set growth after charges and how much to raise your income each year for inflation.
- Enter other income, such as the State Pension, so the tax is right.
How pension drawdown works
In flexi-access drawdown, you can usually take up to 25% of your pot tax-free and leave the rest invested. You then withdraw what you need, when you need it, and each withdrawal is taxed as income. Alternatively you can take lump sums where each one is 25% tax-free (UFPLS). See MoneyHelper: income drawdown.
How long will my pension pot last?
| Starting income | 2% growth | 4% growth | 6% growth |
|---|---|---|---|
| £12,000 | 84 | 89 | 97 |
| £15,000 | 80 | 83 | 87 |
| £18,000 | 78 | 80 | 82 |
| £21,000 | 76 | 77 | 79 |
| £24,000 | 75 | 76 | 77 |
Growth is never smooth. Large falls in the first few years, when the pot is biggest, do the most damage. That is called sequence risk, and it is why many people take a lower income at first or keep a cash buffer.
Pension drawdown tax calculator: tax on withdrawals
Drawdown income is added to your other income and taxed at your normal rates. The first time you take money, your provider will often use an emergency tax code and take too much. Our pension tax calculator shows how much you may need to reclaim. Taking any taxable income also triggers the £10,000 Money Purchase Annual Allowance on future contributions.
Run the pension drawdown calculator with a low growth rate as well as your expected one. If the plan only works with strong returns, consider a lower income or using part of the pot to buy an annuity.
Drawdown vs annuity
Drawdown gives flexibility and lets you pass on what is left, but your income is not guaranteed. An annuity gives a guaranteed income for life. Compare figures with the annuity calculator. From April 2027, unused pension pots are due to count towards Inheritance Tax.
Frequently asked questions
How much can I take from drawdown each year?
There is no legal limit. Many planners suggest starting around 3.5% to 4% of the pot a year, rising with inflation, to reduce the risk of running out.
Is this pension drawdown calculator UK specific?
Yes. It uses UK Income Tax bands, the 25% tax-free cash rule and the £268,275 lump sum allowance.
What happens to my drawdown pot when I die?
It can pass to your beneficiaries. Before 75 it is usually tax-free to them; after 75 it is taxed as their income. Inheritance Tax rules change from April 2027.
Can I move from drawdown to an annuity?
Yes. You can use some or all of your drawdown pot to buy an annuity at any time.
About this calculator
This pension drawdown calculator uses 2026/27 tax rates, checked against MoneyHelper on 9 November 2026. It assumes a steady growth rate and yearly withdrawals at the start of each year. Results are illustrations, not guarantees.